

Earnings Data Surpasses Historical Averages
As of August 7, 88% of companies within the S&P 500 index had reported their financial results for the second quarter. According to data provided by FactSet, 86% of these firms exceeded market expectations for earnings per share (EPS). This performance rate stands notably above historical benchmarks, surpassing both the five-year average beat rate of 78% and the ten-year average of 76%.
John Butters, a senior earnings analyst at FactSet, noted in a research report that if the final tally for the quarter remains at 86%, it would represent the highest percentage of S&P 500 companies reporting positive EPS surprises since the second quarter of 2021. During that period, 87% of companies had beaten estimates.
Beyond the frequency of beats, the magnitude of the outperformance has also been substantial. On an aggregate basis, reported earnings for S&P 500 companies are more than 29% above analyst estimates. This figure indicates a broad-based strength in corporate profitability across the index, rather than isolated gains from a small subset of high-performing firms.
Market Resilience Amid Geopolitical and Economic Headwinds
The strong earnings reports come against a backdrop of significant macroeconomic challenges. The stock market has maintained levels at or near record highs throughout the year, despite facing multiple economic headwinds. These pressures include renewed inflation concerns and geopolitical instability, specifically citing the war in Iran as a factor influencing market conditions.
Despite these external pressures, equity markets have continued to climb. Analysts observe that the recent market performance is not driven entirely by the artificial intelligence sector. While AI-related stocks have been prominent drivers of market valuation in previous periods, the current earnings breadth suggests that financial strength is more widespread across different industries than previously attributed to technology sector dominance alone.
Implications for Investor Sentiment
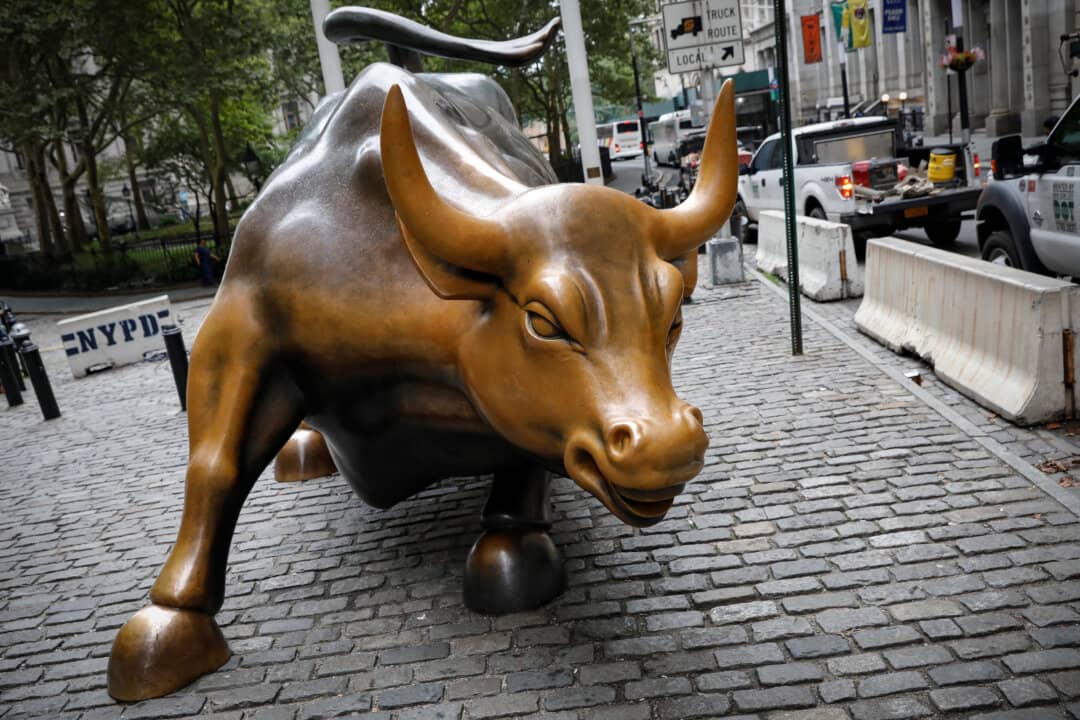
The disconnect between challenging geopolitical conditions and robust corporate earnings has contributed to investor confidence. Wall Street investors have largely disregarded the string of negative economic indicators that typically cause market volatility. The persistence of record-high stock levels, combined with the unexpected strength in corporate profits, has reinforced a bullish outlook among traders.
FactSet’s analysis highlights that the breadth of earnings beats is a critical metric for assessing market health. When a majority of companies exceed expectations, it often signals underlying economic resilience. The 29% aggregate surplus over estimates provides a buffer against potential future economic slowdowns, as companies are generating more cash flow than analysts had projected.
Comparison to Previous Quarterly Performance
The current quarter’s results mark a departure from recent historical trends. While beat rates fluctuate quarterly, the consistency of outperformance in Q2 2024 is distinct when compared to the five and ten-year averages. The proximity to the Q2 2021 peak of 87% suggests that corporate profitability has returned to levels last seen during a period of post-pandemic economic recovery.
However, analysts caution that the final numbers may shift slightly as the remaining companies report their results before the quarter closes. The current data reflects a snapshot taken on August 7, capturing the majority of reporting activity but not necessarily the complete final dataset for the entire index.
Focus on Aggregate Profitability
The aggregate earnings figure of more than 29% above estimates serves as a key indicator of corporate financial health. This metric aggregates the total profits of all reporting companies and compares them to the consensus forecasts made by Wall Street analysts prior to the earnings releases. A surplus of this magnitude implies that corporate guidance was generally conservative, or that actual business performance significantly outpaced even optimistic projections.
The data suggests that inflationary pressures, while present, have not severely eroded corporate margins across the S&P 500. Companies have been able to maintain profitability despite the cost increases associated with renewed price pressures and geopolitical disruptions such as the conflict in Iran.
Analyst Perspectives on Market Drivers
John Butters’ assessment provides a framework for understanding the current market environment. By highlighting the historical context of the 86% beat rate, FactSet positions the current quarter as an outlier in terms of positive earnings surprises. The comparison to Q2 2021 underscores the rarity of such widespread outperformance.
The observation that market performance is not solely reliant on artificial intelligence stocks alters the narrative regarding the drivers of the bull market. Previously, concerns existed that the market was overvalued due to a narrow concentration of gains in tech giants. The broad-based earnings beats indicate that financial strength is distributed more evenly across the index, reducing reliance on a single sector for overall market stability.
As the quarter concludes, investors will monitor whether this trend holds for the remaining reporting companies. The current data provides a strong foundation for Q2 2024 earnings season, characterized by widespread profitability and resilience against external economic and geopolitical challenges.