

Equity Markets Bear Geopolitical Costs
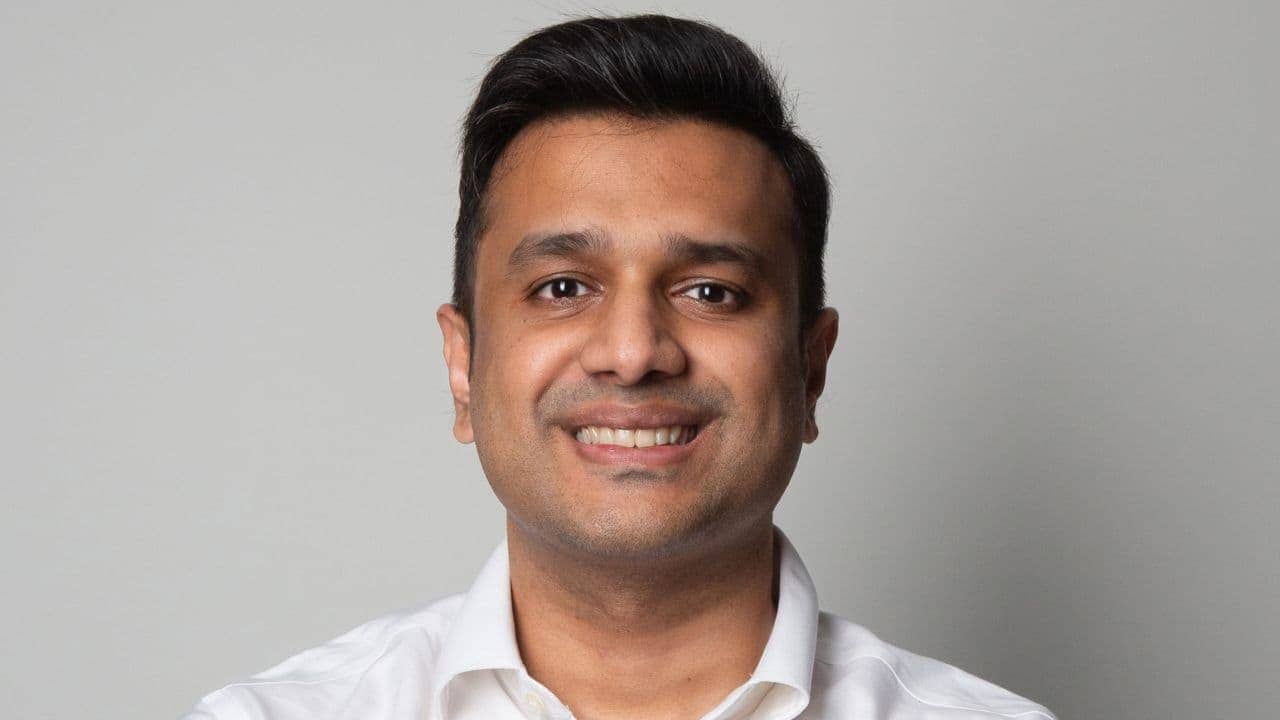
Gaurav Didwania, a fund manager at Qode Advisors, has articulated that equity markets have predominantly absorbed the financial burdens stemming from what he describes as the “geopolitical tax.” This assessment points to a critical dynamic where the costs associated with global political instability are primarily borne by stock investors, rather than being fully disseminated across other economic sectors or directly impacting the broader consumer base through immediate price hikes.
Didwania's insights were featured in an analysis published by Moneycontrol as part of its esteemed Daily Voice segment, a platform known for presenting expert opinions on market trends and economic forecasts. His commentary delved into the intricate relationship between global political instability and the fluctuations of key commodity prices, with a particular emphasis on crude oil. The core of his argument posits that despite the inherent volatility introduced by geopolitical tensions, financial markets possess a remarkable ability to integrate and price in these risks. This integration, however, is contingent upon specific commodity price thresholds remaining unbreached, preventing a broader systemic disruption.
The “geopolitical tax” itself is conceptualized as the cumulative additional economic costs that businesses and consumers face as a direct consequence of international conflicts, trade disputes, or widespread political instability. Didwania’s analysis suggests that over a considerable period, equity investors have effectively shouldered this burden. This absorption mechanism primarily manifests through adjustments in stock valuations and asset prices within the equity markets. Consequently, the immediate and widespread impacts on crucial macroeconomic indicators such as inflation data or national current account balances have been mitigated, at least until certain critical commodity price levels are surpassed.
Investor Resilience Amidst Global Instability
The notion that equity markets absorb this “tax” highlights the role of financial instruments in buffering the real economy from immediate shocks. When geopolitical events unfold, the initial reaction often plays out in stock price movements, reflecting investor sentiment and perceived future risks. This process allows for a gradual pricing-in of uncertainty and potential economic headwinds, rather than an abrupt and widespread economic downturn. Investors, in this scenario, accept lower returns or higher risk premiums, effectively paying the “tax” through their portfolio performance. This mechanism underscores the resilience and adaptive nature of capital markets in processing and internalizing external shocks, provided these shocks do not escalate beyond certain economic thresholds.
Crude Oil Price Thresholds Redefine Economic Outlook
Didwania meticulously detailed specific crude oil price levels that function as pivotal indicators, signaling fundamental shifts in economic calculations and market sentiment. He observed that when crude prices consistently remain below the $85 per barrel mark, their fluctuations are largely perceived as “background noise” within the broader market. In this range, the prevailing energy costs are generally deemed manageable, failing to significantly perturb fundamental economic metrics or necessitate substantial adjustments in monetary policy expectations by central banks.
At prices under $85 a barrel, businesses can often absorb minor increases in energy inputs without drastically altering their pricing strategies or production forecasts. Consumers, too, experience minimal direct impact on their daily budgets from fuel costs, allowing spending patterns to remain relatively stable. For policymakers, this threshold implies that while geopolitical events might cause temporary market jitters, they do not translate into persistent inflationary pressures or current account imbalances that would demand immediate and forceful economic interventions.
Nevertheless, the economic dynamic undergoes a dramatic transformation when crude oil prices sustain levels above $95 per barrel. Didwania's analysis underscores that exceeding this critical threshold fundamentally reconfigures the economic arithmetic that governs both inflation and the current account. The substantial escalation in energy costs at this elevated level introduces palpable and widespread pressures across the economy. These pressures manifest as increased production expenses for industries reliant on oil, from manufacturing to transportation, directly impacting their operational profitability and pricing decisions. Simultaneously, the higher cost of fuel and energy erodes consumer spending power, a key determinant of aggregate demand and a significant driver of inflationary trends.
Energy Costs as a Structural Economic Factor
The clear distinction between these two price points—below $85 and above $95 a barrel—underscores the profound sensitivity of economic models and national financial planning to global commodity markets. Below the $85 threshold, geopolitical incidents that might affect oil supply are typically met with short-term market volatility, which, while noticeable, does not fundamentally alter long-term economic trajectories or growth forecasts. Markets tend to view these as transient disruptions.
Conversely, once crude oil prices breach and sustain the $95 per barrel level, the cost of energy transcends its role as a variable input; it evolves into a structural economic factor. This means that its impact is no longer temporary or easily absorbed. Instead, it necessitates fundamental re-evaluations in national and global financial planning, influencing investment decisions, trade policies, and even long-term energy strategies. Such sustained high prices can lead to a more entrenched form of inflation, making it harder for central banks to manage and potentially leading to broader economic slowdowns as businesses and consumers grapple with persistently higher costs.
Macroeconomic Stability and Policy Responses
The profound shift in economic arithmetic identified by Didwania carries direct and significant implications for overall macroeconomic stability. When crude oil prices are successfully contained below the $95 per barrel threshold, central banks and other financial institutions typically possess the flexibility to interpret any temporary energy price spikes as transient anomalies. This allows them to maintain a steady monetary policy course, avoiding knee-jerk reactions to what are perceived as short-lived market fluctuations.
However, the scenario dramatically alters when prices sustain levels above this critical benchmark. Such prolonged elevation in crude oil prices compels a fundamental reevaluation of inflation forecasts by monetary authorities. This reevaluation is not merely an academic exercise; it often precipitates a shift towards more hawkish monetary policies, including potential interest rate hikes, aimed at curbing persistent inflationary pressures that are now seen as more deeply embedded in the economy. The challenge for central banks intensifies as they navigate the trade-off between controlling inflation and supporting economic growth, with high energy costs often acting as a drag on the latter.
Impact on National Current Accounts
Beyond inflation, current account balances are also directly and substantially impacted. A country's current account measures its transactions with the rest of the world, encompassing trade in goods and services, income flows, and transfers. For nations that are net importers of crude oil, a sustained increase in global oil prices translates directly into significantly higher import bills. This surge in import costs invariably widens their trade deficits, which in turn adversely affects their overall current account balance. A deteriorating current account can signal underlying economic vulnerabilities, potentially leading to currency depreciation, depletion of foreign exchange reserves, and increased external borrowing requirements, all of which can strain national finances and investor confidence.
Didwania’s analysis further distinguishes between how markets initially process these risks and their eventual manifestation. He implies that markets tend to price in the potential for geopolitical disruptions and their associated energy cost increases gradually, often through subtle adjustments in asset valuations and investor expectations, as long as prices remain below the critical $95 threshold. However, once this threshold is decisively crossed and sustained, the financial impact ceases to be a speculative risk and becomes an immediate, quantifiable reality reflected in broader economic data, such as official inflation figures and published current account statistics. This transition marks a point where the “geopolitical tax” moves beyond equity market absorption and begins to exert its influence on the real economy.
The fund manager’s comprehensive comments serve as a crucial directive for investors and policymakers alike. They suggest that crude oil prices should be monitored not merely as another commodity indicator, but rather as a primary and highly sensitive gauge for determining when geopolitical tensions transcend market-specific volatility and begin to materially affect the fundamental health and stability of the global economy. The precise transition from being mere “background noise” to becoming a defining and structural economic factor is, according to Qode Advisors, unequivocally marked by these specific price points.