Equity Markets Hold Steady Amid Uncertainty
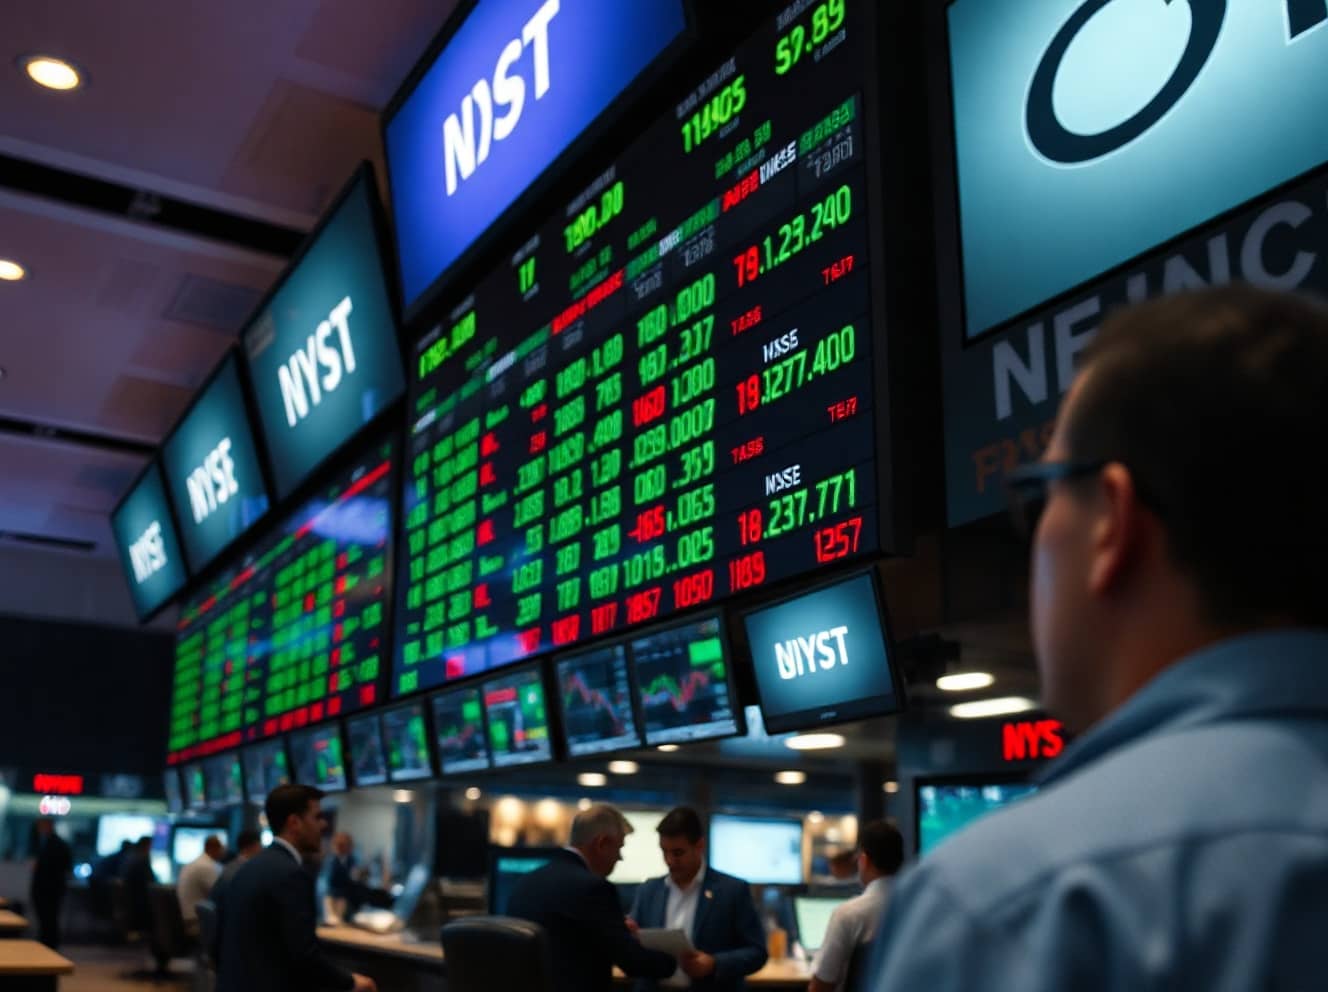
Global equity markets remained locked in a narrow trading range on [Date], as investors juggled escalating geopolitical risks, volatile oil prices, and shifting expectations for Federal Reserve policy. This period of constrained market activity occurred just before the anticipated release of the latest Consumer Price Index (CPI) report, a key economic indicator widely expected to set the tone for the next phase of the market cycle.
Investor sentiment across global bourses has been characterized by a palpable sense of caution, reflecting the convergence of multiple complex economic and geopolitical factors. This cautious approach has led to a lack of clear directional momentum, with market participants hesitant to commit significant capital ahead of crucial data. According to reports from BitcoinWorld, the intricate interplay between these diverse variables has kept stocks in a churning state, where price movements are often confined within tight boundaries, preventing any definitive trends from emerging prior to the critical inflation data release.
This narrow trading range suggests that while there isn't a widespread sell-off, there's also little conviction for a sustained rally. Investors are carefully weighing the potential for external shocks against domestic economic signals, leading to a period of consolidation as they await clearer signals regarding inflation's trajectory and central bank responses.
Geopolitical Tensions Drive Oil Price Premium
Ongoing conflicts in key energy-producing regions have significantly contributed to elevated crude oil prices, thereby creating a complex and challenging environment for global trade and the calculation of inflation metrics. These geopolitical tensions have not only threatened but, in some instances, caused tangible supply disruptions. Such disruptions, whether actual or merely perceived as a strong possibility, have introduced a substantial risk premium into the global oil market, further complicating the broader inflation outlook for economies worldwide.
Brent Crude Prices Remain Elevated
Brent crude prices are hovering near $[XX] per barrel as of [Date], maintaining a high level that underscores the market's sensitivity to geopolitical instability. The sustained elevation of Brent crude is directly attributed to the persistent threat of broader escalation in these conflict zones. This includes concerns over potential disruptions to vital shipping lanes or direct impacts on oil production facilities. Such an elevation in energy costs serves as a crucial floor under oil prices, exerting continuous upward pressure on existing economic models that are built upon assumptions of stable and predictable energy inputs.
The integration of this geopolitical risk premium into oil pricing means that inflation calculations are no longer solely driven by traditional factors such as domestic demand or monetary policy adjustments. Instead, they are now heavily influenced by external supply shocks and the perceived stability of global energy flows. This dynamic forces market participants, including corporations and analysts, to significantly adjust their forecasts for both corporate earnings, which face higher input costs, and consumer spending power, which is eroded by increased fuel and energy expenses. The ripple effect extends across various sectors, from manufacturing and transportation to retail, all grappling with the direct and indirect consequences of higher energy prices.
Federal Reserve Policy Expectations Shift
Beyond the immediate impacts on physical commodity markets, financial markets are acutely reacting to evolving expectations regarding the Federal Reserve's monetary policy. The central bank's stance and approach to interest rates remain an exceptionally critical variable, directly influencing asset valuations across all classes, from equities to bonds. As geopolitical risks persist and contribute to inflationary pressures, particularly those stemming from elevated energy costs, the Fed's potential responses are being monitored with intense scrutiny by investors and economists alike.
Shifting expectations for Federal Reserve policy indicate that market participants are actively reassessing the timeline and magnitude of potential rate adjustments. This reassessment is driven by a confluence of factors, including incoming economic data, statements from Fed officials, and the perceived resilience of the economy in the face of external shocks. The uncertainty surrounding these pivotal policy moves adds yet another significant layer of volatility to equity markets, which are already grappling with the tangible and immediate impacts of high oil prices on corporate profitability and consumer behavior. The market is keenly watching for any signals that might suggest a deviation from previously anticipated rate paths, whether that implies delayed cuts, fewer cuts, or even the remote possibility of further tightening if inflation proves more stubborn than expected.
Inflation Data Sets Stage for Next Market Phase
The upcoming Consumer Price Index (CPI) report is universally viewed as a pivotal moment for determining the immediate future trajectory of financial markets. This crucial data release is expected to provide much-needed clarity on whether the inflationary pressures currently observed, particularly those originating from energy and other supply-side sources, are becoming entrenched within the broader economy or if they remain transient and likely to dissipate over time. The distinction between entrenched and transient inflation has profound implications for central bank policy and investment strategies.
Analysts widely note that the CPI report holds the potential to decisively set the tone for the next phase of the market cycle. Should the data reflect persistent inflation, especially if it is significantly driven by the aforementioned geopolitical instability and supply-side factors, it may compel a fundamental re-evaluation of Federal Reserve policy expectations. Such a scenario could lead to a more hawkish stance from the Fed, potentially delaying interest rate cuts or even prompting discussions of further tightening. Conversely, the release of cooler-than-expected inflation data could provide a significant measure of relief to equity markets, potentially alleviating some of the current pressure and allowing them to break out of their prolonged narrow trading range, possibly signaling a more favorable environment for growth assets.
Until the CPI data is officially released and its implications fully absorbed, global equity markets are broadly expected to remain in a state of suspension, characterized by cautious trading and limited conviction. The convergence of geopolitical instability, persistently high oil prices, and profound monetary policy uncertainty creates an exceptionally volatile and unpredictable environment where traditional valuation metrics, based on historical performance, may prove less reliable than forward-looking indicators that attempt to price in future risks and potential policy shifts.