

Gold Rebounds From One-Year Low Amid Cooling Inflation Fears
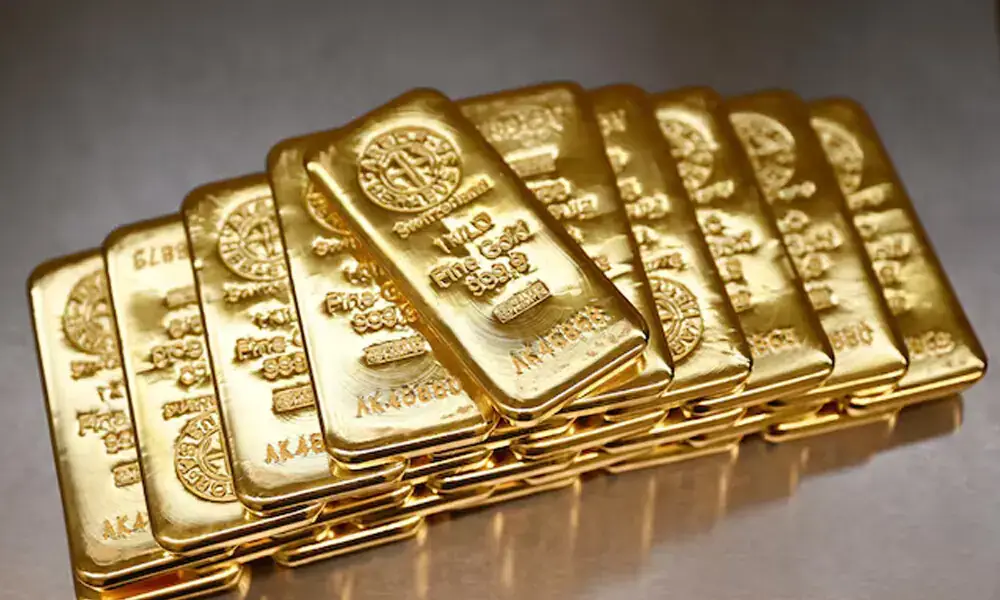
Gold prices staged a significant recovery on Monday, rising more than 2% to rebound from a one-year low hit in the previous session. The rally was primarily supported by softer oil prices, which helped temper lingering inflation worries that had previously weighed on precious metals. Spot gold rose 2.1% to $3,957.19 per ounce at 10:49 a.m. ET, marking a sharp reversal from Friday’s close where the metal had ended 3.6% lower and hit its lowest level since October 2025.
US gold futures for December delivery also participated in the upward movement, rising 1.77% to $3,967.40 per ounce. The technical picture for the metal improved markedly during the session; gold’s 14-day Relative Strength Index rose to about 37 on Monday, climbing from below 30 on Friday. This shift indicated that the metal had emerged from technically oversold territory, providing a foundation for the day's gains.
Peter Grant, vice president and senior metals strategist at Zaner Metals, noted that weaker oil prices provided relief regarding inflation concerns. However, he cautioned that the market still expected a December rate hike from the Federal Reserve. Data from CME Group’s FedWatch Tool showed that traders see a 77% chance of a US rate hike in December, down slightly from 80% a week ago, suggesting that while expectations remain firm, the probability is gradually shifting.
Geopolitical Tensions and Market Volatility Drive Safe-Haven Demand
The recovery in precious metals occurred against a backdrop of complex geopolitical developments. Oil prices fell more than 6% on Monday after Iran and Qatar held a third consecutive day of talks aimed at ending the US-Israeli war on Iran. This drop in energy costs played a dual role in the market: it reduced immediate inflationary pressure but also highlighted the fragile state of global stability.
Earlier in the week, market dynamics were heavily influenced by a selloff in technology and AI-linked stocks that spilled across markets on Friday. This sell-off triggered margin calls that led to sales of safe-haven assets such as gold, creating a temporary paradox where investors liquidated their hedges to cover losses elsewhere. The subsequent rebound suggests that the initial panic-driven selling has subsided, allowing fundamental factors like inflation expectations to take precedence.
Attention is now shifting to the November 3 US midterm elections to assess potential impacts on fiscal policy, geopolitics, and broader market sentiment. Carsten Menke, an analyst at Julius Baer, stated that the fiscal backdrop in the US is unlikely to change significantly enough to make a difference for gold, as deficits should persist regardless of the midterms outcome. This view suggests that while political outcomes will influence other asset classes, the structural demand for gold may remain insulated from immediate legislative shifts.
Broader Precious Metals Rally and Historical Election Context
The recovery was not limited to gold. Spot silver climbed 3.7% to $50.91 per ounce after breaking below $50 for the first time since late November 2025 in the last session. Similarly, spot platinum rose 1.9% to $1,457.96, while palladium was steady at $976.13. Both platinum and palladium had bounced from their lowest levels in 13 and 17 months, respectively, on Friday, indicating a broad-based relief rally across the precious metals complex.
As markets digest these price movements, historical data regarding midterm elections is being closely monitored. Markets historically herald strong performance for stocks after midterm elections, regardless of whether it is a red or blue wave, split decision, or status quo in Washington. An analysis of S&P 500 returns from 1980 through 2024 by CNBC showed that the index rose an average of 0.2% after one day and one week, and 1.1% after one month across both presidential and midterm elections.
The long-term historical record is even more pronounced. A year later, the S&P 500 gained an average of 13.7% after midterms and 13.8% after presidential elections, with returns positive in 91% of cases. Notably, the S&P 500 was up after all 11 midterms from 1982 through 2022. Ryan Detrick, CNBC contributor and chief market strategist at Carson Group, observed that there is anxiousness before elections, but once passed, markets tend to do pretty well due to relief.
Political Dynamics and Sector-Specific Risks
The nature of the election outcome also appears to influence market reactions. Across 10 midterm and five presidential elections that left no single party in charge, the S&P 500 rose an average 15% after one year, with positive returns in 14 out of 15 cases. Detrick noted that markets do not like huge red or blue waves as much because of too much spending and power concentration; a divided government is usually preferred.
Specific scenarios have shown distinct patterns. After three midterms (1986, 1990, and 2006) where Democrats controlled both houses and a Republican held the presidency, the S&P 500 averaged a 0.5% decline on the reaction day but was up 3.4% a month later and 10.9% after a year. However, Société Générale emphasized that Federal Reserve policy and the corporate earnings cycle ultimately matter more than elections for market performance.
Historical precedents also highlight the role of monetary policy over political outcomes. Stocks declined in the aftermath of the 2018 midterms when Democrats wrested control of the House, as the Fed tightened monetary policy by raising interest rates four times, ending the year down 6.2%. This underscores that while elections create short-term volatility, macroeconomic forces often dictate longer-term trends.
Looking ahead, the intersection of technology and politics remains a critical variable. Ryan Detrick identified the big swing factor now as AI and whether declines in tech will continue; as long as the AI wave is moving and the economy grows, the bull market is likely still alive. However, he warned that a Democratic sweep of the House and Senate would almost certainly pressure the AI infrastructure buildout and could lead to more retrenchment.
Despite the historical optimism surrounding post-election periods, caution remains warranted. Jim Reid, Deutsche Bank's global head of macro and thematic research, cautioned that seasonality isn't destiny, and worries around Iran, AI, and France won't mysteriously vanish. Investors are navigating a landscape where geopolitical tensions, monetary policy expectations, and technological shifts continue to interact in complex ways.