

Treasury Yields Breach Key Threshold Amid Market Volatility
The benchmark 10-year Treasury yield has crossed the 5% threshold, marking a significant movement in fixed-income markets. This rise in yields comes as higher interest rates and ongoing geopolitical risks contribute to increased volatility across financial markets. The breach of the 5% mark places bond yields at their highest level since 2007, according to market data referenced in recent reports.
The surge in yields has prompted renewed discussion among investors regarding the current state of the fixed-income market. Some analysts note that terms such as "price cushion" and "escape velocity" are becoming more relevant as bond investors evaluate whether the current environment presents an opportunistic moment for entry. The movement reflects broader concerns about the trajectory of interest rates and their impact on asset pricing.
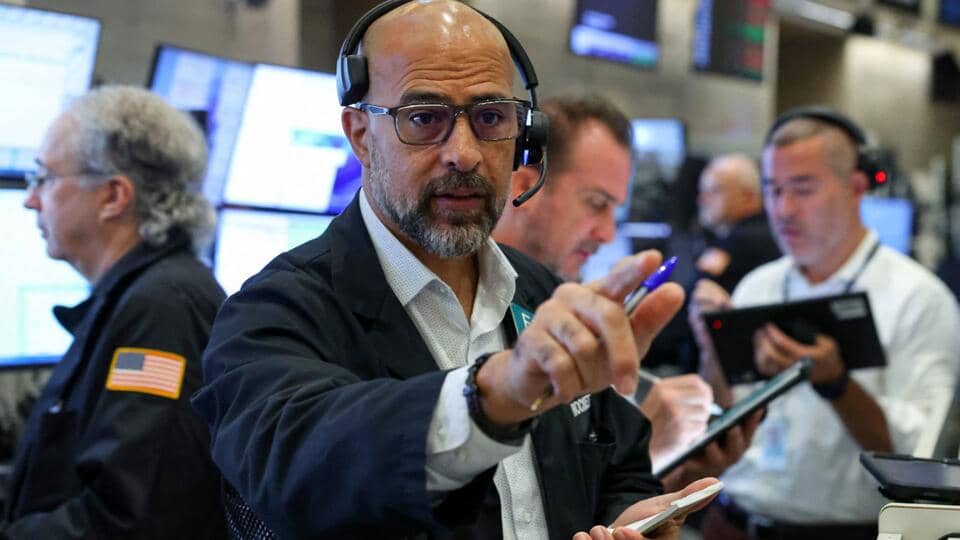
Despite the pressure from rising yields, equity markets have not experienced the sell-off that some analysts had anticipated. Investors continue to hold positions in stocks, suggesting a divergence between bond market pressures and equity market resilience. This dynamic has drawn attention from financial experts who are monitoring how long equities can maintain their footing against the headwinds of higher borrowing costs.
Fund Managers Remain Overweight on Global Equities
Contrary to expectations that rising rates would trigger a retreat from stocks, recent data indicates that institutional investors are maintaining their exposure to global equities. According to Bank of America’s latest fund manager survey, investors remain overweight in global equities. The survey highlights a persistent confidence in the stock market despite the challenging macroeconomic environment characterized by spiking bond yields and elevated oil prices.
The Bank of America survey also revealed that investors are optimistic about corporate earnings. This optimism appears to be a primary driver for the continued allocation to stocks, even as the cost of capital increases. Fund managers are weighing the potential for earnings growth against the headwinds of higher interest rates, with the current sentiment leaning toward the former.
Market participants are closely watching how this dynamic evolves. The persistence of equity holdings suggests that investors believe the fundamental drivers of stock prices, such as corporate profitability, may outweigh the negative impacts of rising bond yields in the near term. This stance contrasts with more cautious approaches seen in other asset classes where uncertainty is higher.
AI Spending Cited as Growth Catalyst
In addition to general earnings optimism, specific sectors are drawing interest from major financial institutions. Investors including BlackRock and UBS have pointed to artificial intelligence spending and demand as factors that could continue to support economic growth. These firms suggest that the capital expenditures associated with AI infrastructure may provide a buffer against broader market volatility.
The focus on AI-related investments reflects a belief that technological advancement can drive productivity and revenue growth independent of traditional economic cycles. By attributing potential growth to this sector, major asset managers are signaling that structural changes in the economy may be supporting equity valuations even as monetary policy tightens.
Expert Perspectives on Rate Hikes and Market Strategy
Financial experts are offering varied perspectives on how investors should navigate the current landscape. Dan Niles, founder of Niles Investment Management, discussed the implications of a potential rate hike cycle on CNBC’s "Squawk on the Street." Niles advised that investors should not fight the Federal Reserve or the bond market, suggesting that alignment with central bank policy and fixed-income trends may be prudent.
This advice underscores the tension between equity optimism and bond market realities. While fund managers remain overweight in stocks, the guidance from some experts emphasizes caution regarding interest rate movements. The divergence between investor positioning and expert commentary highlights the complexity of the current market environment.
As bond yields continue to fluctuate near the 5% level, investors are balancing the optimism surrounding earnings and AI-driven growth against the risks posed by higher rates and geopolitical instability. The coming weeks will likely provide further clarity on whether the current equity resilience can be sustained or if the pressure from fixed-income markets will eventually force a reallocation of assets.