

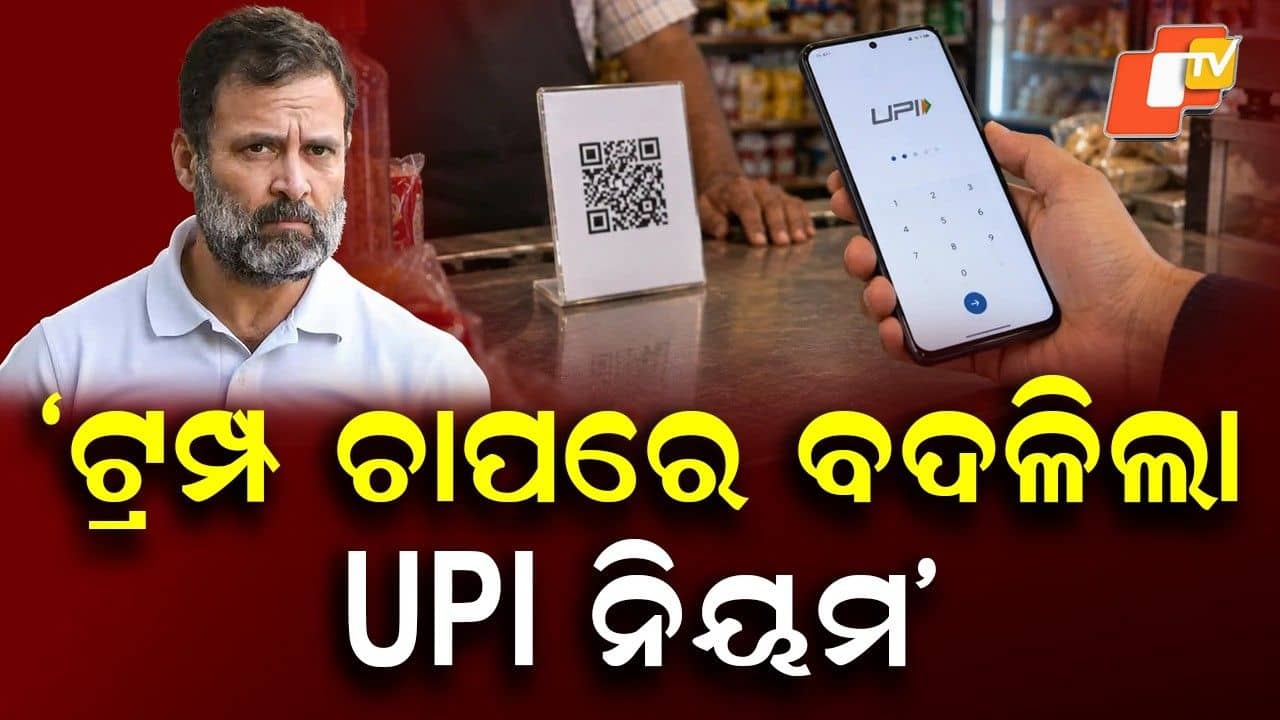
Congress Leader Challenges New UPI Fee Structure
India’s Unified Payments Interface (UPI) payment system, a cornerstone of the nation's digital economy, is scheduled to undergo a significant regulatory adjustment beginning on October 15, 2026. This upcoming rule change introduces a Merchant Discount Rate (MDR) of 0.4% applicable to specific merchant transactions exceeding ₹2,000. This modification marks a departure from the long-standing policy that has largely kept digital payments free for users and merchants alike, a factor widely credited for UPI's explosive growth and widespread adoption across diverse economic strata.
Congress leader and Leader of the Opposition Rahul Gandhi has publicly criticized the impending change with strong rhetoric. Gandhi described the new fee structure as a "Trump tax," alleging that the decision was introduced under pressure from the United States. He called for the immediate withdrawal of the MDR, framing the policy shift as an externally driven imposition rather than a domestic economic decision aimed at strengthening India’s financial infrastructure. His comments have ignited a political debate, questioning the autonomy of India's digital payment policy.
The Evolution of India's Digital Payments Landscape
Since its launch, UPI has revolutionized financial transactions in India, offering instant, interoperable, and free digital payments. Its accessibility has been a key driver in fostering financial inclusion, allowing millions of citizens, from urban professionals to rural vendors, to participate in the digital economy. The system's zero-MDR policy for a long period was instrumental in encouraging both consumers and merchants to adopt digital transactions over cash, contributing significantly to the government's broader agenda of a less-cash economy. The proposed introduction of an MDR, even on a limited scale, signals a pivotal moment in the evolution of this widely used payment rail.
Specifics of the October 15 Policy Shift
The new guidelines specify that the 0.4% Merchant Discount Rate will apply only to designated merchant transactions above the ₹2,000 threshold. This means that smaller transactions, which constitute a large volume of daily UPI usage, will remain unaffected by the new charge. The National Payments Corporation of India (NPCI) and relevant regulatory bodies have clarified that person-to-person (P2P) UPI transfers, a common method for direct money transfers between individuals, will continue to be free of charge, ensuring that personal financial interactions are not burdened by the new fee. Furthermore, a crucial detail emphasized by authorities is that the MDR is not intended to be directly charged to consumers at the point of sale; instead, it will be borne by the merchants.
The implementation date for these changes is firmly set for October 15, 2026. This policy adjustment significantly affects how merchants and payment service providers manage costs within the digital transaction ecosystem. While consumers are not directly charged, the potential for merchants to indirectly pass on these costs through product or service pricing remains a point of contention and a focus of the ongoing political debate. Gandhi’s opposition highlights a growing political debate over the financial sustainability of India’s digital public infrastructure versus concerns about potential hidden costs or perceived foreign influence on domestic policy.
Government Rejects Allegations, Cites Sustainability Goals
The government has firmly rejected Rahul Gandhi’s allegations regarding US pressure influencing the UPI fee change. Officials have stated unequivocally that the decision to implement the MDR is an autonomous, domestic policy choice aimed at making the UPI ecosystem financially sustainable in the long term. The administration emphasized that the fee structure is a strategic economic measure designed to support the continuous development and long-term viability of payment networks, rather than a concession to foreign entities or external demands.
By introducing a nominal discount rate on larger transactions, authorities argue that the system can better support the substantial infrastructure, ongoing maintenance, and continuous innovation required to maintain its global standing as a leading digital payment platform. The government maintains that this approach balances the critical need for revenue generation to fund technological upgrades and security enhancements with the continued accessibility and affordability of digital payments for the general public, especially for everyday transactions.
Political and Economic Implications of the MDR
The controversy surrounding the UPI fee change underscores the inherent political sensitivity of digital payment policies in India. As UPI has evolved into a widely adopted tool for financial inclusion and a symbol of India's technological prowess, any alteration to its cost structure attracts immediate and intense scrutiny from opposition parties and consumer advocates alike. Rahul Gandhi’s characterization of the move as a "Trump tax" reflects broader concerns among critics about the potential influence of international trade dynamics and geopolitical pressures on local economic regulations and public services.
Supporters of the policy, including government officials and financial sector experts, argue that the MDR is a necessary step to address the escalating operational costs associated with maintaining a robust, secure, and constantly evolving digital payment network. They contend that without such revenue streams, the system may struggle to fund future technological upgrades, enhance cybersecurity measures, and expand its reach to underserved populations. The debate continues as the October 15, 2026, deadline approaches, with both sides presenting their cases to the public regarding the optimal future trajectory for digital transactions in India, balancing innovation, accessibility, and financial self-sufficiency.