

US Long-Term Yields Surge to 24-Year High Amid Fiscal Concerns
The United States witnessed a significant shift in its bond market on Tuesday, September 29, 2026, as long-term Treasury yields climbed to their highest levels in over two decades. According to data from the US Treasury, the 30-year Treasury yield closed at 5.59%, marking a notable increase from the previous day's close of 5.56%. This surge represents the highest closing level for the benchmark bond since June 2002.
Intraday trading saw further volatility, with the Financial Times reporting that the 30-year yield touched an even higher point of 5.61% during afternoon trading in New York. The movement underscores a growing skepticism among investors regarding the long-term trajectory of US debt and the economic policies driving it.
The rise in yields is not occurring in isolation but is part of a broader macroeconomic environment characterized by persistent inflationary pressures and robust economic data. Drivers for this upward trend include oil prices remaining above $100 a barrel throughout September, which continues to influence inflation expectations. Additionally, the US public debt has now exceeded the $40 trillion mark, a milestone that has heightened concerns about fiscal sustainability.
Compounding these issues is the Federal Reserve's recent monetary policy decision. The central bank raised interest rates in September 2026, marking its first increase since 2023. This move signals a continued fight against inflation but also contributes to the rising cost of borrowing across the economy. Market participants are reacting swiftly to this hawkish stance; futures markets are currently pricing in four additional quarter-point rate rises over the next year.
Investor Sentiment Shifts as Term Premium Rises
The dynamics of bond ownership are changing as the term premium for long-term debt continues to rise. Arun Sai, an analyst at Pictet Asset Management, noted that investors are not eager to add duration to their portfolios under current conditions. This reluctance suggests a broader hesitation to lock in long-term yields when uncertainty about future rate paths remains high.
International perspectives on US bonds also appear to be cooling. Kristina Hooper of Man Group highlighted that US bonds may lose appeal for foreign buyers due to the country's fiscal path and the unpredictability of its foreign policy. This loss of confidence among international investors could exacerbate the pressure on yields, as reduced demand typically leads to lower prices and higher yields.
Despite the turbulence in the bond market, equity markets have shown relative resilience, though they are not immune to the headwinds. The S&P 500 index fell 0.3% on Tuesday, yet it remains only 2% below its record high set in August. This narrow gap indicates that while investors are wary of fixed-income assets, they have not yet fled equities entirely, perhaps betting on continued economic strength despite the rising cost of capital.
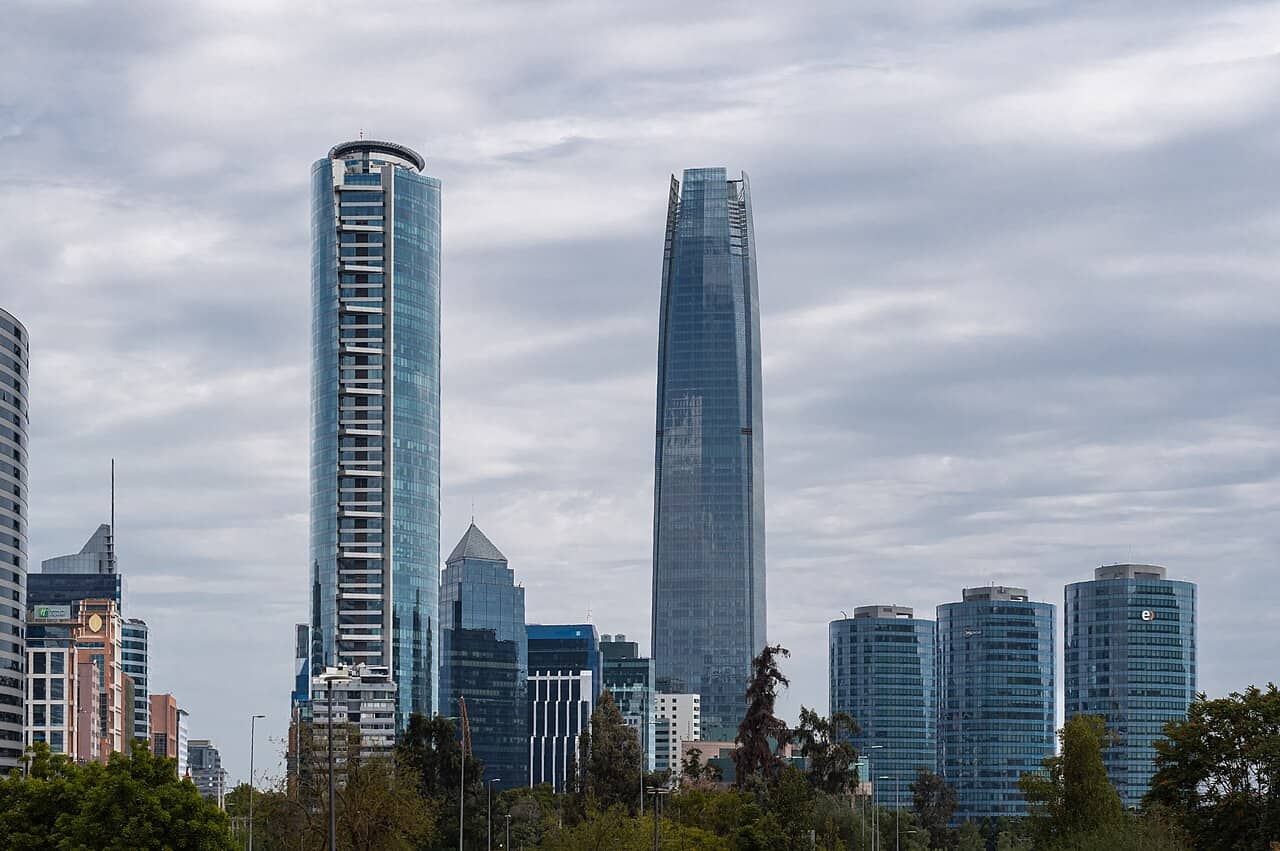
Chilean Peso Hits 13-Month Low Against Dollar
While US bond markets grappled with record highs, currency markets in South America experienced significant volatility. The Chilean peso closed at 973.4 per dollar on September 29, 2026, marking a 13-month low and its weakest level since September 2, 2025. Bloomberg reported that the dollar rose by 4.2 pesos to reach this closing figure against the Chilean peso.
The depreciation of the peso reflects broader global trends where the US dollar's strength, fueled by rising yields and safe-haven demand, puts pressure on emerging market currencies. The combination of high US interest rates and domestic economic factors in Chile has contributed to this downward spiral for the local currency.
Looking ahead, there are expectations for a potential stabilization or recovery. Banco Santander Chile has projected that the peso could strengthen gradually towards 910 per dollar by the end of 2026, provided that geopolitical tensions ease. This forecast suggests that while current conditions are challenging, external factors such as global political stability play a crucial role in determining the currency's future trajectory.
Domestic Economic Indicators Signal Caution
The economic backdrop in the United States also shows signs of cooling, which contrasts with the strong data that has previously supported higher yields. The Conference Board reported that the US consumer confidence index hit its lowest level since 2014. Furthermore, job openings missed forecasts, indicating a softening labor market.
These mixed signals—strong inflation data driven by oil prices and debt concerns on one hand, and weakening consumer confidence and labor demand on the other—create a complex environment for policymakers and investors alike. The 10-year Treasury yield also saw movement, closing at 5.26%, which matches its peak from June 2007, further illustrating the long-term nature of the current yield curve pressures.
As markets digest these developments, the interplay between fiscal policy, monetary tightening, and global geopolitical risks will likely continue to dictate asset prices in both bond and currency markets. The record highs in US yields and the lows in the Chilean peso serve as stark reminders of the interconnectedness of global financial systems and the sensitivity of investors to shifts in economic fundamentals.